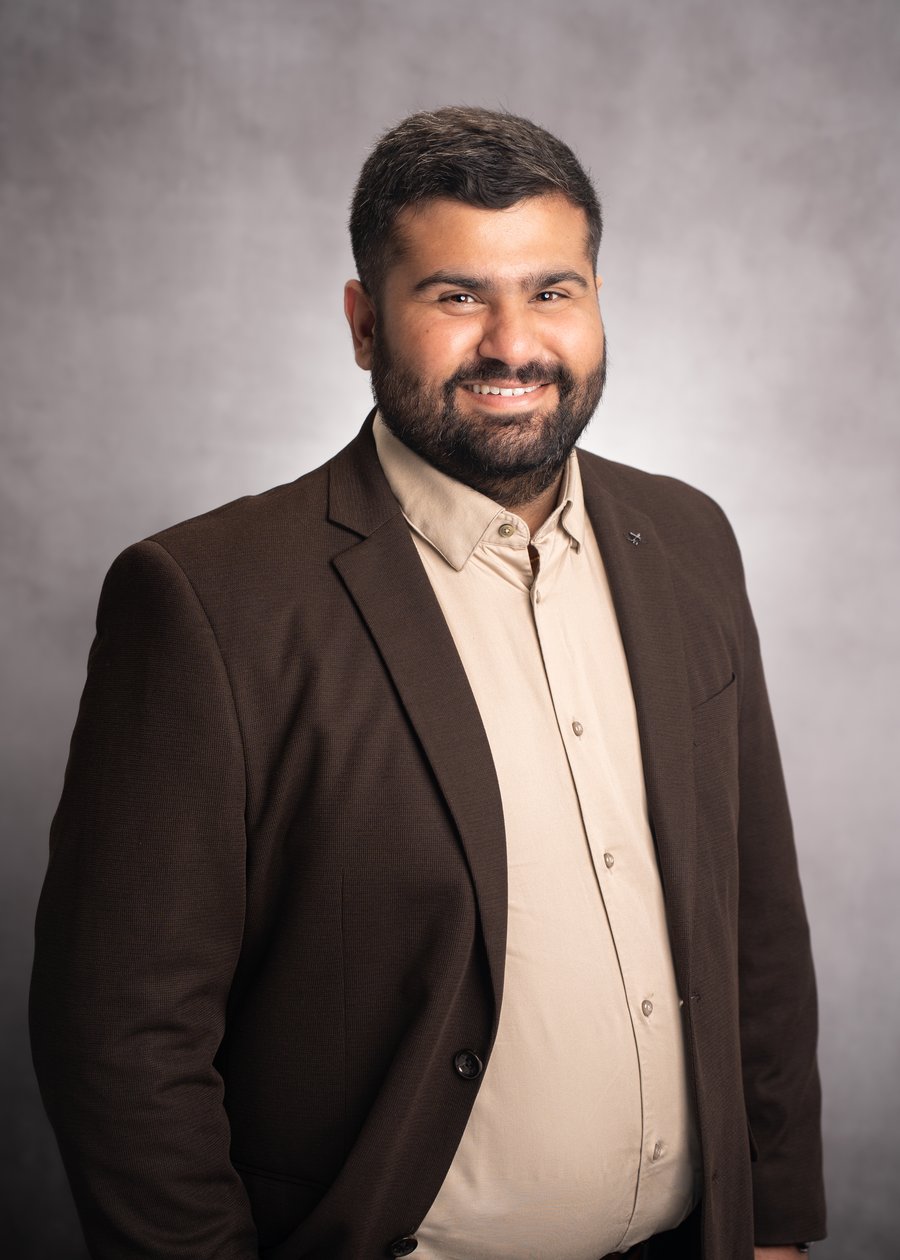
Licensed Mortgage Agent · Ontario
I work directly with you — comparing options across 65+ lenders to find a mortgage that actually fits your income, your goals, and your timeline. Whether it's your first purchase or your fifth commercial deal, you deal with me, not a call centre.
Apurva Sindhi
Mortgage Agent, Level 1
Lic. #M25002184 · 8Twelve Mortgage Corp
Before mortgages, I spent seven-plus years in retail and QSR management, building teams and getting people to results under real pressure. That's the same thing I bring to your mortgage: someone who manages the process closely, communicates clearly, and doesn't disappear once you've signed something.
As a licensed Level 1 Mortgage Agent with 8Twelve Mortgage Corp, I work across the full range of residential and commercial lending — from first-time buyers and renewals to self-employed borrowers, private financing, and commercial purchases and refinances. If a bank has already said no, or made you feel like a number, that's usually where I can help most.
Based in Oakville, Ontario — working with clients across Mississauga, the GTA, and Canada.
What I help with
Every deal is different. Here's the full range of what I work on day to day — residential, commercial, and everything in between.
From pre-approval to keys in hand. I walk you through down payment options, FHSA/RRSP (Home Buyers' Plan) incentives, the Land Transfer Tax rebate, and every document the lender needs — explained plainly, not in bank-speak.
Access the equity you've built, restructure your existing mortgage, or lock in a better rate before your term is up. I run the numbers first — including penalty costs — so a refinance only happens when it actually leaves you ahead.
Don't auto-renew with your bank without a second opinion — most people leave money on the table doing that. I compare the full market before your term ends and handle the switch paperwork if a different lender wins.
Turn the equity in your home into an open, reusable line of credit — for renovations, investing, or a financial cushion. I'll show you how much you likely qualify for and how it compares to a refinance for your situation.
When you need funds fast, or a bank has said no, a second mortgage or private lender can still get a deal done. I'll tell you plainly when this route makes sense, what it costs, and when it doesn't — no upselling.
Roll high-interest credit cards, car loans, or personal loans into your mortgage at a mortgage-level rate. Often the single biggest monthly cash-flow fix available to a homeowner carrying multiple debts.
Purchases and refinances for commercial, mixed-use, and multi-unit residential property, structured around the way the business or the property actually generates income — not a cookie-cutter residential application.
Financing for rental and investment properties, including how rental income is factored into what you qualify for, and how a portfolio of properties is best structured across lenders over time.
If a bank declined you because your income doesn't fit a standard T4 box, I work with lenders who actually underwrite self-employed, commission, and business-for-self (BFS) income — using the documents you already have.
Know your real budget before you shop — a pre-approval locks in a rate hold (typically 90–120 days) so you're protected if rates move while you're house-hunting.
Free tools
Quick estimates to help you plan — for exact figures based on your full financial picture and current lender rates, let's talk.
Estimated monthly payment
$0
Estimate only, based on a standard fixed rate with semi-annual compounding (the Canadian norm) and monthly payments. Actual payment depends on the lender, product, and your full application.
Estimated max home price
$0
Estimate only, using standard GDS/TDS guideline ratios and a rough property-tax/heating allowance. Your real approval depends on the lender's guidelines and full application — this is a starting point for a conversation, not a pre-approval.
Estimated land transfer tax
$0
Estimate only, based on standard Ontario/Toronto brackets for residential property up to $2,000,000. Properties above $2,000,000 in Toronto have additional rate tiers — contact me for an exact figure. Always confirm final closing costs with your real estate lawyer.
Estimated equity available
$0
Estimate only, based on the standard 80% combined loan-to-value limit for refinances and HELOCs in Canada. Actual amount depends on appraisal, lender guidelines, and income qualification.
Why work with me
Questions get answered by the person actually working your file — usually the same day.
Major banks, credit unions, monoline and alternative lenders — compared side by side, not just whichever bank you already use.
I'm paid by the lender once your mortgage funds — not by you. My advice isn't shaped by which bank pays best.
How it works
20–30 minutes to understand your goals, your income situation, and your timeline.
I compare rates and terms across 65+ lenders and bring you the options that actually fit.
I handle the lender negotiation and paperwork, and keep you posted at every stage.
Mortgage funded — and I stay reachable after closing for renewals, refinances, or questions.
Where I work
Get started
Pick a time that works for you — no pressure, no obligation.
Widget not loading? Open the calendar in a new tab.
PREFER TO REACH OUT DIRECTLY?
(705) 905-5595Call or text apurva.sindhi@8twelve.mortgageEmail @mortgage.with.apurvaInstagram DM